
Yo Pit Crazies,
I wish I were better at AI.
I'd build a boxing ring and drop Warsh and Trump in it like the old Knock-Your-Block-Off boxers.
Warsh needs to prove he'll let rates float to wherever the market puts them. Trump and Bessent want them lower before the midterms.
The FOMC (the Fed's rate-setting committee) decides Wednesday at 2 p.m., and I'm calling a 3% move in SPDR S&P 500 ETF (SPY) on the day.
This is one of my rare posts where politics and the stock market cross paths, because right now it matters.
As Frank Gregory says, all money runs through DC, and he's not wrong.
Bessent spent Tuesday testifying in front of the House while the Fed sat down across town to decide whether to hike.
Here's the setup: Futures price a roughly 90% chance the Fed raises a quarter point Wednesday, the first hike since July 2023. On Sunday the President said the U.S. should pay the lowest interest rate in the world. The midterms sit seven weeks out.
Outside the AI doomsday essays and oil, most things run fine. Corporate profits jumped $400.9 billion in the second quarter, more than five times the first-quarter gain, and after-tax margins hit a record. AI has been very good for business.
The big haze last year was tariffs, and that's mostly settled. The reason for them, after all, was to raise money for a Treasury taking on the proportions of Jabba the Hutt. The 10-year yield hit 5.04% Tuesday, its highest since 2007, and Congress just punted the budget fight to December 11.
Oil is the other problem.
Iran still has Hormuz mostly shut, the Houthis declared an embargo on Saudi shipping, and the Saudis closed a pipeline after drone attacks. Talks on the Strait got postponed Sunday and Brent crossed $107 Monday, which fed the hot August CPI and PPI prints that pushed hike odds to 90%.
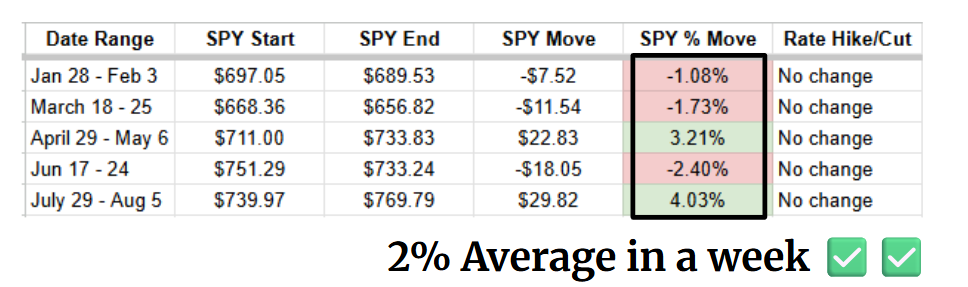
Above is what happened in 2026. A 2% move is the average week this year, with the granddaddy rally in early August. The S&P 500 closed at a record 7,737 on August 4 and closed at 7,585 Tuesday, under the August levels, and the VIX (the market's fear gauge) at 17 says sentiment runs about where it did then.
Traders couldn't believe we rallied 4% in a week last month, and we have short memories. I think we do it again this week, with a 3% move on FOMC day. There'll be a relief rally one way or the other, and here's why:
- AI isn't going away, whatever the doomsday essays say.
- The bond market controls rates, and Congress is tone deaf.
- Warsh won't restart QE (the Fed printing money to buy bonds and push rates down).
- President Trump has the midterms to deal with and a Republican Congress that's near useless.
My oddball call: President Trump cares more about ending the Iran conflict properly, meaning U.S. control of the Strait of Hormuz, than about getting lazy Republicans elected. That doesn't mean he won't try to make things happen if rates don't go his way.
That gives us quite a move this week.
3% on SPY Wednesday. You heard it here first.
Hope this was helpful,
Andrew Giovinazzi