We’re in the middle of a major shift in the markets.
Wednesday’s CPI ran hot. Headline inflation jumped to 3.7%, and core came in at 2.6%, both a tick above forecasts. Then Thursday’s PPI came in a lot hotter. Producer prices rose 1.3% in September, the biggest monthly gain since March 2022, and core PPI rose 0.7% when the Street was looking for 0.3%.
Any other week this year, numbers like that would’ve crushed bonds. Industrials and old-line companies would’ve sold off, and money would’ve rushed into big tech, especially AI. Instead, bonds rallied.
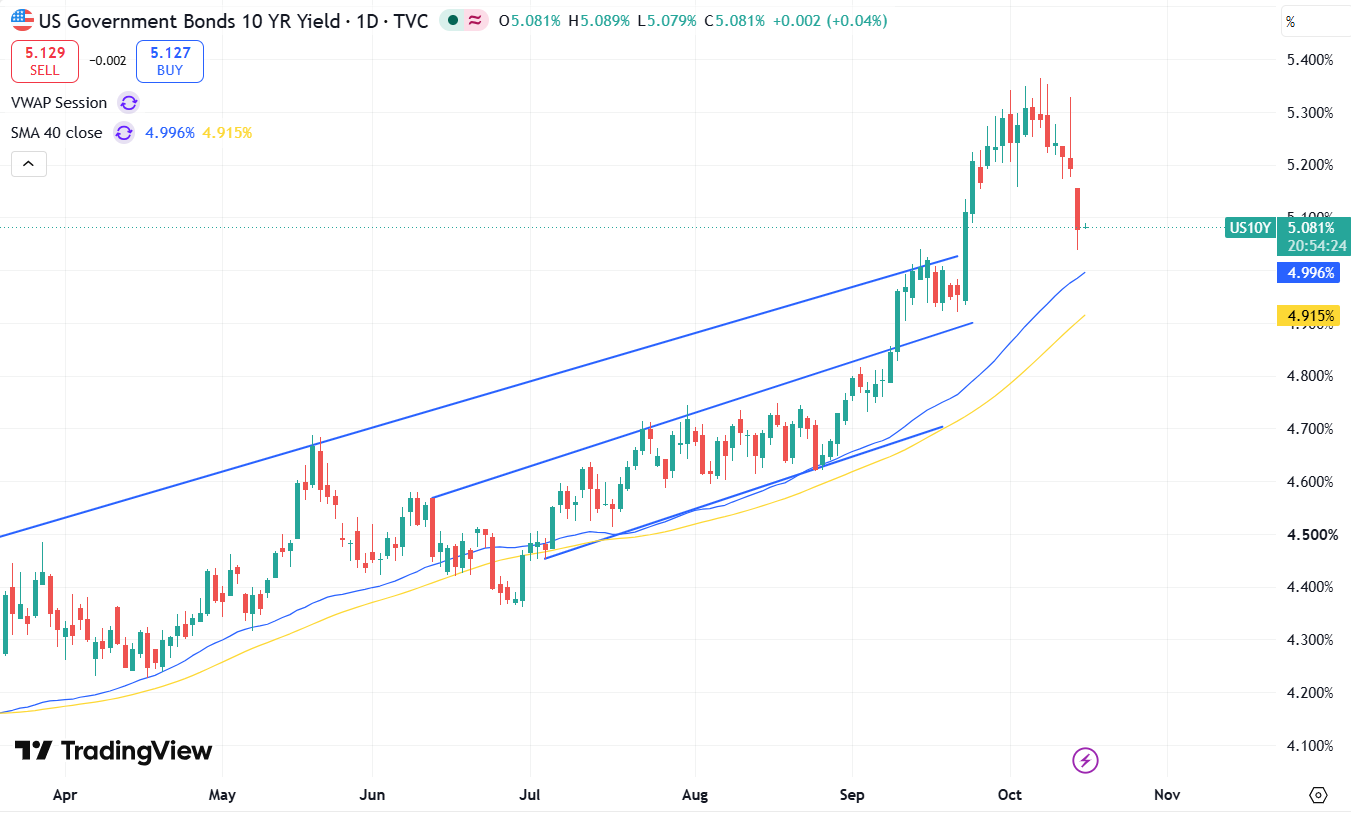
The 10-year yield touched 5.33% after the CPI release Wednesday. By Thursday it had dipped to about 5.04% before settling near 5.06%. That’s the biggest one-day drop in more than a year, and it’s a multi-standard-deviation collapse in yields.
With bonds popping and yields falling, industrials and all the boring stuff in the stock market took off. The Dow gained 1% on Thursday. Meanwhile, the QQQ has been in free fall. If it weren’t for a late rally Thursday, we’d be talking about whether the QQQ might actually touch its 200-day moving average for the first time since April.
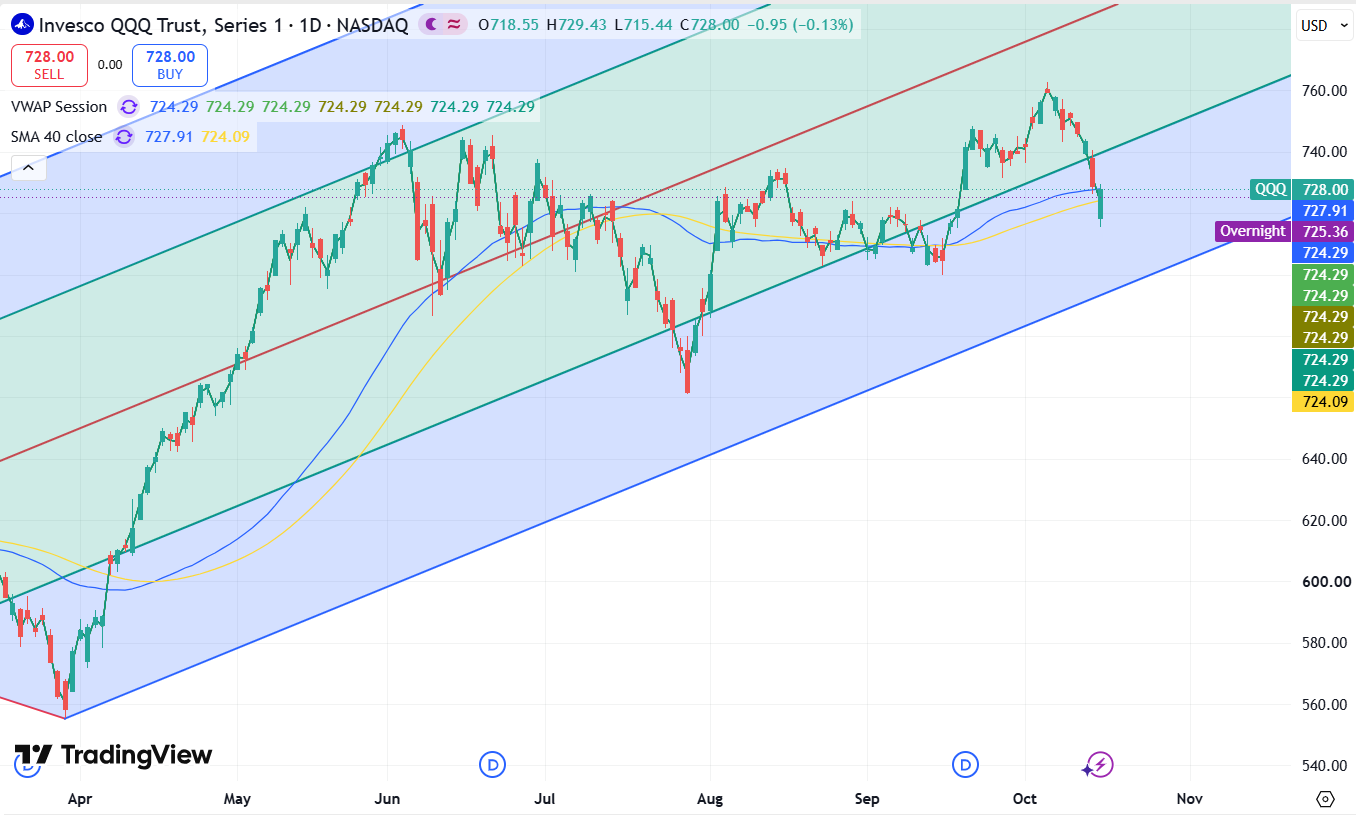
Money’s racing into bonds while it bails on chips, memory, and anything tied to OpenAI. That started on Oct. 8th, when the Financial Times reported OpenAI’s annualized revenue is running about $20 billion below what investors had been told. Big tech has shed more than $1 trillion in market value in a week.
That’s bad news for any AI trade that isn’t directly tied to Anthropic, and I think Anthropic sees some real action over the next month heading into the IPO.
Near term, I like RSP and DIA, I’m neutral on the SPX, and I’m bearish on the NDX.
I think strangles in the QQQ could pay nicely.
Somebody in Omaha Agrees With Me
If rates keep dropping, housing gets a significant boost. Homebuilders have been one of the worst places to have money this year, if not the worst. Mortgage rates hit 7.3% at the end of September, close to a three-year high, so this drop in the 10-year is the first real relief the group has gotten in a while.
Lennar (LEN) is barely off its 52-week low. It printed a fresh one Wednesday in the low 70s, about 43% below last December’s high of $131.61. Ten analysts rate it a sell, and only one rates it a buy. Morgan Stanley started coverage on Oct. 1 with an underweight and a $65 target.
Berkshire Hathaway doesn’t seem to care. It bought another $192.6 million of Lennar on Oct. 1 and 2 alone and now owns about 12% of the company, a stake worth roughly $2.2 billion. That’s more than double what it held at the end of June.
Lennar’s also set up to move fast when rates turn. It owns less than 2.5% of the roughly 488,000 lots it controls and holds options on the rest, so it isn’t sitting on a mountain of land if the turn takes longer than I expect.
If the 10-year keeps falling, this sector could explode higher. I think rates have a nice week, and this is one to buy.
Let Somebody Else Hold It Into the 29th
Until Intel (INTC) reports, the entire chip sector’s going to stay soft. Intel reports third-quarter results after the close on Oct. 29, which gives the bears almost two more weeks to lean on it.
The stock’s already down about 20% from its September high, and it’s been fighting to hold $100 after falling in six of seven sessions into Monday. It still trades at 63 times forward earnings, more than three times Nvidia’s 19. Intel Foundry lost $2.09 billion last quarter, and management plans to spend more than $20 billion on capex this year. And earlier this month, Elon Musk confirmed he’s talking to TSMC about joining Terafab, the chip project Intel signed onto in April.
Good news hasn’t been enough to save it, either. Intel tripled the Street’s Q2 earnings estimate in July, and the stock still fell 7.9% the next day.
I’d want to be out of the trade before earnings, but ahead of earnings I like buying puts on INTC. I think the stock could fall below 90.
If it does, Intel becomes a screaming buy.
The question is, do either one of these become the baby behind Monday’s option pick of the week for the Ticker Highlight Show?
Last week, Hans took the honors and closed out a 118% gain in around two days.
See what the next one does for yourself by tapping this link and paying whatever you want to join the Ticker Highlight Show.