

Hey There Income Hunters,
It’s finally over …
It was just over a year ago that the Fed began a rate hiking cycle that was second to only Paul Volcker’s late 70’s early 80’s cycle.
Today, we will likely see a .25% rate hike while Powell retains his hawkish bias.
The bigger concern is obviously the regional banks going forward – that’s where the real story is.
Higher rates and the inverted yield curve are killing the banks.
Today, I’ll lay out the 4 reasons why the banking system is in such dire need of rate cuts.
1 – Quantitative Tightening Kills Bank Revenues
Quantitative tightening is even more damaging to banks than rate hikes because it reduces bank reserves.
The QT drains a bank’s reserves held at the Fed. Bank’s borrow against the reserves to make loans and also for liquidity in the markets business.
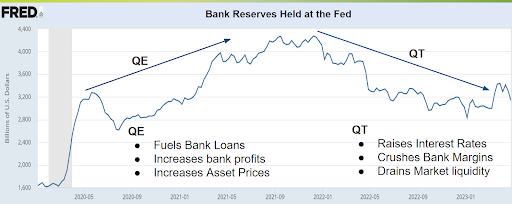
When liquidity in markets dries up while bank loan standards are tightening it has a very dampening impact on economic activity.
QT ultimately triggers a credit crunch in the system, by causing job losses and defaults on debt.
The Fed will soon be forced to lower rates to counter this trend and disregard the inflation fight.
2 – Deposit Runs on Banks
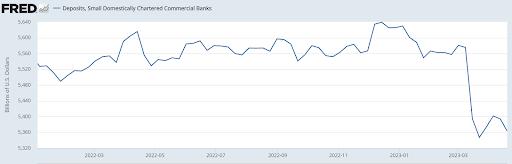
There are two issues incenting customers to pull their deposits from smaller banks.
First, they get paid very little interest on them.
Second, they fear the bank will fail. And there is now a fear that FDIC is under capitalized, and it will take a long time to get their money back.
Notice the drop off of nearly $350 billion in deposits since the failure of Silicon Valley Bank (Ticker: SIVB).
3 – The Inverted Yield Curve
By raising the Fed Funds Rate, the Fed puts much more pressure on the short-term interest rates and less on longer-term rates.
This causes the yield curve to shift into backwardation or an inverted slope. Notice the red circle in the bottom right corner of the chart below. This illustrates the steepest inversion in the yield curve in 40 years.
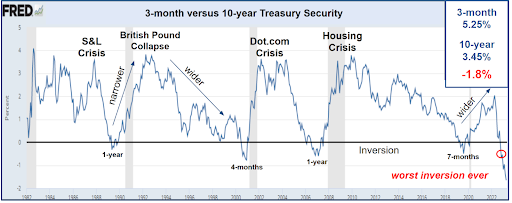
An inverted curve crushes bank profit margins because banks borrow short-term to invest in long-term rates.
So, they are unable to make enough of a spread to counter the credit risk in the loans they issue.
4 – Loses On Their Bond Holdings
In 2022 as bond yields soared higher, the banks accumulated massive unrealized losses on their holdings:
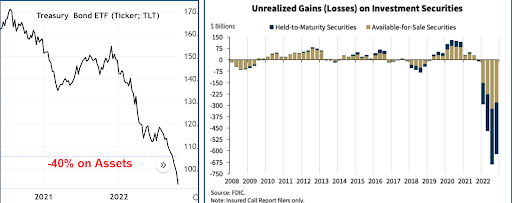
The losses are estimated to be near $650 billion. The banks are in a terrible position as inflation remains sticky, which puts pressure on rates.
This is the strongest case for the Fed to begin lowering rates in the months ahead.
Powell has continued to point to employment strength in the economy as the reason they can continue to raise rates …
However, this banking crisis is spreading and the financial system MUST take center stage in their thought process.
For these reasons, I believe the next move will be a cut in rates and it may come sooner than the market is currently pricing in.
Live and Trade With Passion My Friend,
Griff