
BY ANDREW GIOVINAZZI
July 24th, 2025
Yo Pit Crazies,
You’re probably thinking of Hans’ MTI—no doubt it’s been fueling his wild winning streak lately. But this one’s different. It’s centered around the VIX, and in terms of risk-reward, it’s the most compelling setup I’m seeing right now.
The SPDR S&P 500 ETF (Ticker: SPY) just hit yet another all-time high, and the volatility on the at-the-money strike in the August 15th regular expiration cycle is sitting at 12.09%.
Time to pay attention.

But you might be thinking—”wait, VIX is at 15”, so why is the at-the-money implied volatility just 12% for options about a month out?
It’s giving me serious Roberta Flack vibes: Where is the Love?

But instead, I have to ask—where’s the vol?
The answer? It’s all in the VIX futures
VIX futures are priced so high right now that about 17% of the value in volatility products is just extra cost above what they’re really worth. That’s like pure juice with no water added. For something like the iPath Series B S&P 500 VIX futures ETN (Ticker: VXX), a product that tracks VIX futures, a lot of its price comes from this extra ‘bonus’ value. But here’s the catch—it can all disappear by the time the futures expire.
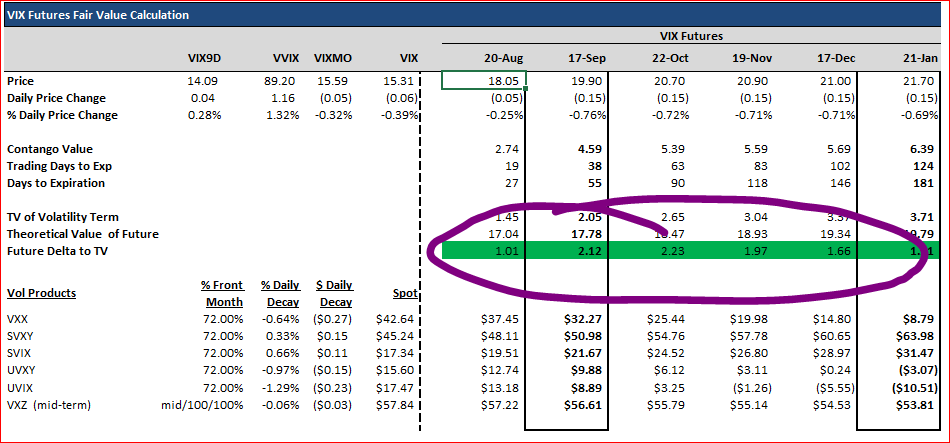
Traders are still on edge, waiting for the upcoming Fed decision and the August 1st trade deadline. That’s keeping forward volatility elevated. It takes more effort for VIX to drop from high levels than to rise from low ones—and the VIX futures are reflecting that. The current setup also suggests that VIX futures are positioned to absorb a fair amount of bad news.
Right now, strangle pricing on volatility products like VXX looks ideal. That’s what I was focused on today, and I’ll be watching it closely again tomorrow.
To Your Trading Success,
AG
