Hey Traders,
Thursday looked rosy.
The S&P 500 and the Nasdaq both climbed back above their 50-day moving averages (the average close of the last 50 sessions, a line plenty of fund managers watch).
Many traders started hunting for a repeat of the face-ripping rally we saw in late July.
It didn't happen.
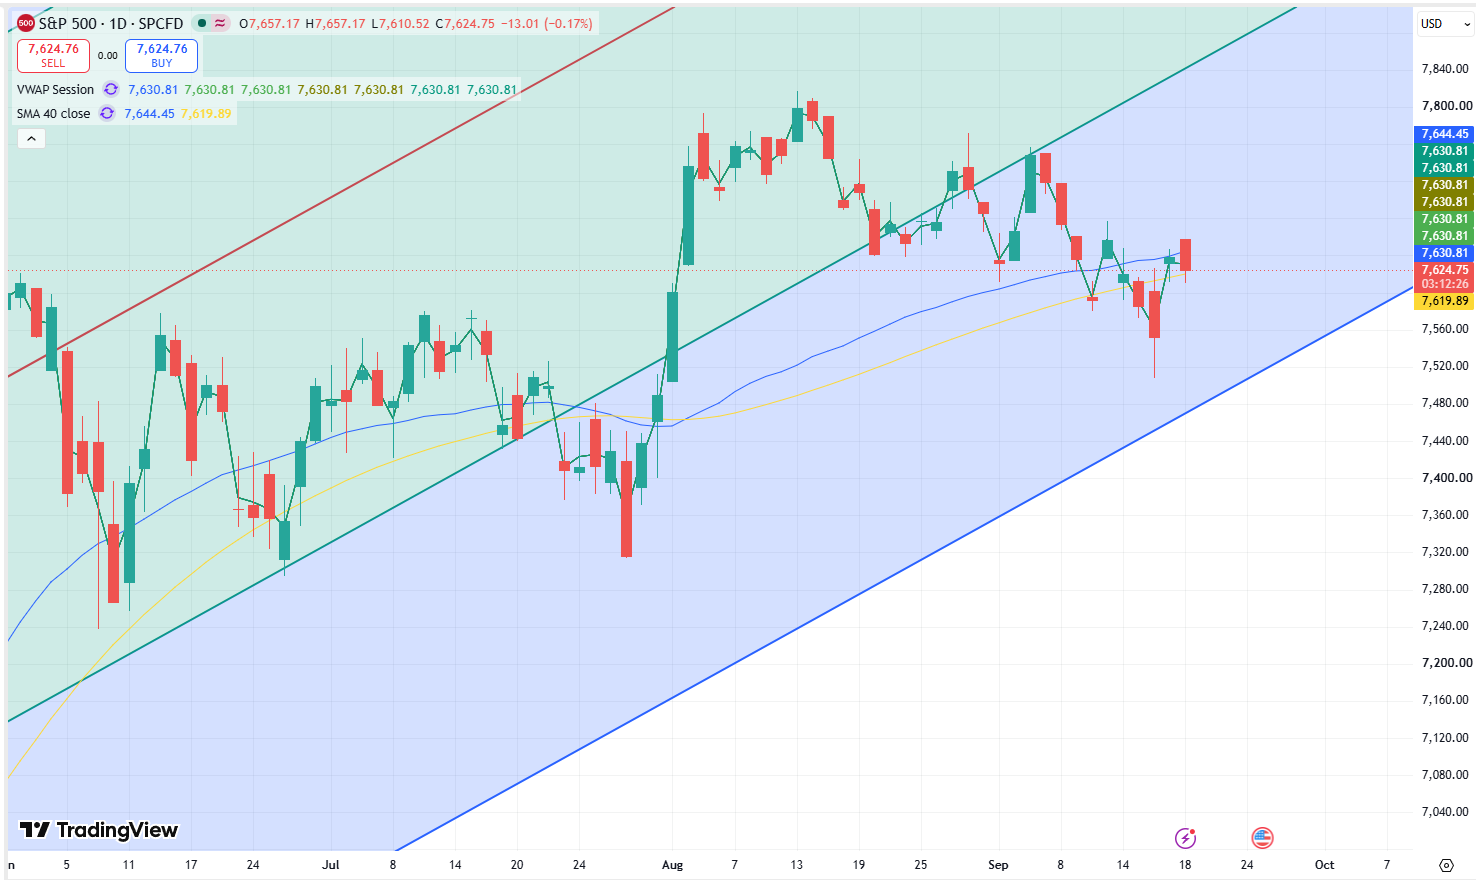
The S&P opened Friday at its high of the day, sold off into lunch and scratched out a 0.17 percent gain by the bell. The Dow finished red, and the S&P lost ground for the week. Compare that with the session after July's FOMC meeting, when stocks went on a RIP.
I see one big difference between the two. On July 30, the day after the Fed decision, Japan launched its largest currency intervention in 15 years, and that yen buying landed in the same session as the post-Fed rally. This time we got no intervention. The Bank of Japan raised rates Friday morning to a 31-year high instead, and bond yields rose around the world.
So I think we remain stuck in the pattern of the last few weeks.
We get BIG BIG up days, and then mostly slow, grinding down days.
One thing in this tape really concerns me. Oil has driven yields higher for weeks. WTI crude topped $106 on Tuesday and settled Friday at $100.30, a slide of about $6 in three sessions.
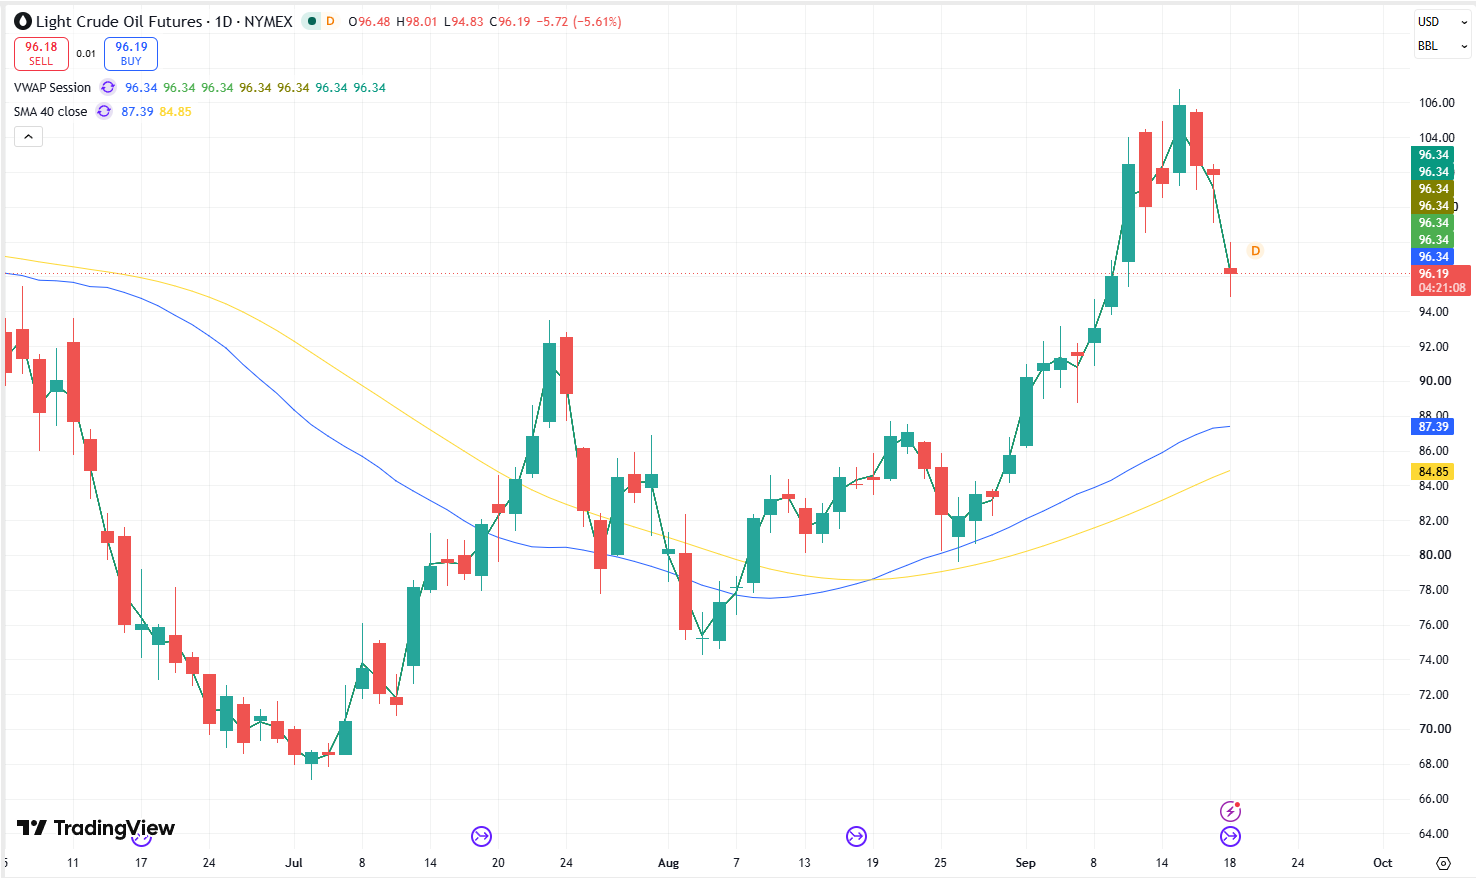
You'd expect bonds to rally with crude coming off like that, since the two have moved together. They haven't. The 10-year yield didn't close at its high of the week, but it went right back to 5 percent on Friday, and the bulls should NOT like that.
Meanwhile the VIX (the market's gauge of expected S&P 500 swings) closed at 14.81. I can assure you of one thing: index options cost too little given the downside risk and the upside catapults we've seen.
The Back Door Into October's Biggest Deal
Amazon (AMZN) holds the biggest outside stake in Anthropic, and the stock has only started to catch a bid. It gained one percent Friday while the S&P barely moved.
Most traders don't grasp the size of this position. Amazon carried its Anthropic holdings at $190.4 billion in its June filing, based on a $965 billion valuation. Reports now have Anthropic seeking something close to $2 trillion in its IPO.
Reuters has the public prospectus landing in late September, with the roadshow (the stretch when management pitches big investors) starting around mid-October. I expect AMZN to rally as the excitement builds through both. We saw a lot of bullish flow in the name over the past few days, and I like the stock back to 265 to 270 at a minimum.
That doesn't ask much. AMZN traded above 267 within the last month and hit a record 287 in early August.
Kicked Out of the Club After 18 Years
Nike (NKE): nothing goes right here. The stock and the management team have completely lost their way. Shares closed Friday at $35.51, a fresh 52-week low, down 78 percent from the 2021 peak.
Kylian Mbappé walked out on Nike for On Holding on Friday, and the S&P 100 drops the stock before Monday's open after an 18-year run. UBS cut its target to $42 on Wednesday and said global sales growth has deteriorated.
The most valuable piece of the brand now sits with Jordan, which runs on a man (albeit the GOAT) who hasn't played meaningful professional basketball since the '90s. Even Jordan has started to slip. CEO Elliott Hill told investors in June that Jordan streetwear has struggled to sell through, which forces discounts and shrinks future orders.
Don't call it cheap, either. Strip out a one-time $986 million tariff refund and Nike earned $1.58 a share last fiscal year, which puts the stock near 22 times earnings. Converse sales fell 31 percent over that year, and Greater China dropped 17 percent in the latest quarter.
The company needs a major shake-up, and it reports again October 1. I think it goes to 30, and I see put buyers who agree with me.
The question is, will either one of these two picks make the cut on Monday at 10:30 AM ET on the Ticker Highlight Show? Tap this link to sign up and get the next trade.